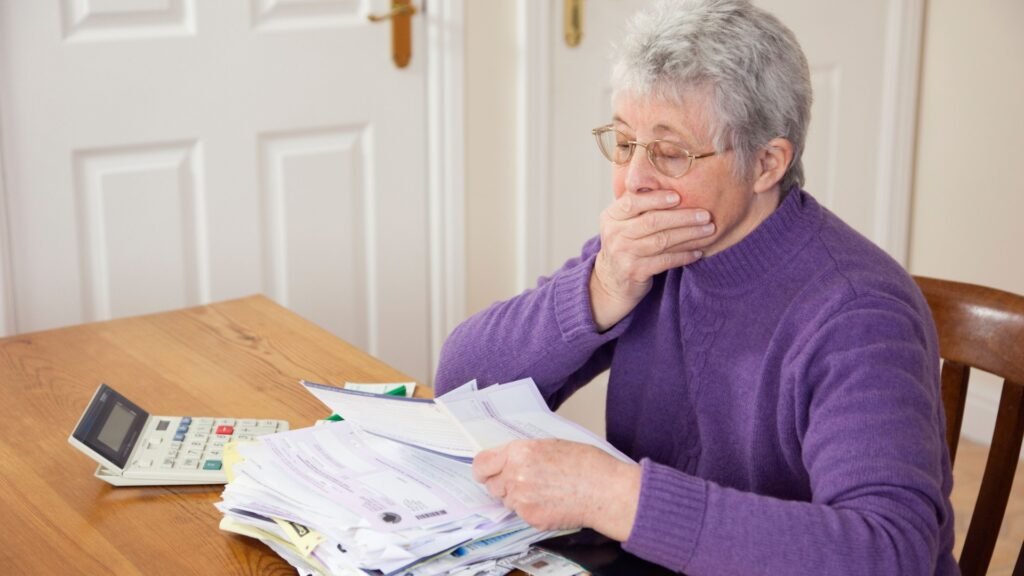

MILLIONS of retirees are set to pay tax on their state pension for the first time from April, as just one in 16 benefit from a key exemption.
In November the Chancellor announced that anyone whose income comes solely from the new state pension will not be forced to pay tax on it for the rest of this Parliament.
The full new state pension is worth £12,548 a year, but it is expected to rise to £13,036 a year from next April.
This would put it above the £12,570 threshold at which you begin to pay income tax.
Sign up for the Money newsletter
Thank you!
Income tax thresholds are frozen until 2031, which means as the years go on more of your state pension income will be dragged over this threshold.
The measures will save an affected pensioner around £88 in 2028/29 and £220 in 2029/30.
PENSION WINDFALL
Amount YOUR state pension is set to go up by next year under triple lock
POT LUCK
Self-employed? Ultimate guide to boost your pension & get up to £12k FREE cash
But of the 13.2 million people who currently receive a state pension, analysis by pensions consultancy LCP suggests that just 700,000 pensioners, or one in 16, will benefit from the change.
None of the 7.7million pensioners on the old state pension will qualify, the firm’s analysis suggests.
The old state pension is currently worth £9,614 a year and is paid to men born before April 6, 1951 or women born before April 6, 1953.
It is forecast to rise by £374.40 to £9,989 a year.
Around 6.5million people on the old state pension also get “additional” state pension, which tops up their income.
As a result, these payments could drag their total income above the income tax threshold.
But under the Government rules only people who rely on the state pension as their sole income and don’t get any top ups will qualify for the tax break.
This means that a pensioner on the old state pension whose payments add up to exactly the same amount as someone on the new state pension will have to pay tax.
Meanwhile, of the 5million people who receive the new state pension, more than four in five people would not qualify.
Approximately 1.8million of this number have other taxable income, such as private pensions or investment income.
This means that they are not solely dependent on the state pension, so won’t qualify.
Around 1.1million receive too little new state pension to be dragged above the tax threshold in the next three years.
What are the different types of pension?
WE round-up the main types of pension and how they differ:
Personal pension or self-invested personal pension (SIPP) – This is probably the most flexible type of pension as you can choose your own provider and how much you invest.
Workplace pension – The Government has made it compulsory for employers to automatically enrol you in your workplace pension unless you opt out.These so-called defined contribution (DC) pensions are usually chosen by your employer and you won’t be able to change it. Minimum contributions are 8%, with employees paying 5% (1% in tax relief) and employers contributing 3%.
Final salary pension – This is also a workplace pension but here, what you get in retirement is decided based on your salary, and you’ll be paid a set amount each year upon retiring. It’s often referred to as a gold-plated pension or a defined benefit (DB) pension. But they’re not typically offered by employers anymore.
New state pension – This is what the state pays to those who reach state pension age after April 6 2016. The maximum payout is £241.30 a week and you’ll need 35 years of National Insurance contributions to get this. You also need at least ten years’ worth to qualify for any cash.
Basic state pension – If you reach the state pension age on or before April 2016, you’ll get the basic state pension. The full amount is £184.90 per week. The exact number of years of National Insurance contributions you need to get this sum varies depending on when you were born. If you have the basic state pension you may also get a top-up from what’s known as the additional or second state pension. Those who have built up National Insurance contributions under both the basic and new state pensions will get a combination of both schemes.
A further 1million people in this group receive extra payments on top of their new state pension payments.
Meanwhile, a further 0.29million are not based in the UK so are not eligible.
Sir Steve Webb, a former pensions minister and partner at LCP, said: “This is politically embarrassing for the Government, but the proposed solution is deeply flawed.
“It discriminates against those on the old state pension system, even if they have identical income to someone on the new system.”
Sir Steve adds that the rules risk creating a cliff edge, where just £1 of extra income could push you over the edge.
As a result, you would have to pay income tax not just on that £1 but also the income tax on their state pension – a further £88.
Over time this cliff edge will only increase and could reach £220 in 2029/30.
Meanwhile, if you have even a small private pension pot then you won’t be considered to be “solely” dependent on the state pension, so you will miss out.
This means that even a small pension pot could cost you hundreds of pounds in extra tax by 2029/30.
Without proper consideration, the policy risks creating an unfair tax write-off that will create unfairness between those with modest incomes.
What are the solutions?
Sir Steve suggests there are two solutions to the problem.
The first is an increase in the tax allowance for all pensioners, which would mean someone who is wholly dependent on the new state pension would be under the tax threshold.
But this would be a windfall to all taxpaying pensioners, including the 8.7million who already paid tax this year.
As a result, the cost could exceed £2billion by 2029/30, which could be unaffordable.
Another option is to write off small tax bills for pensioners.
For example, HM Revenue and Customs could simply not issue tax bills for sums of £88 or less, which would benefit people on the old and new state pension.
But it still risks creating a cliff edge if people had small amounts of taxable income that took them above this figure.
A HM Treasury spokesperson said: “Anyone whose only income is the full new or basic State Pension without any increments will not pay income tax and we are committed to that over this Parliament.
“By keeping the Triple Lock, 12 million pensioners will see their income rise by up to £470 this year, and they continue to benefit from the highest Personal Allowance in the G7.”